Market Overview:
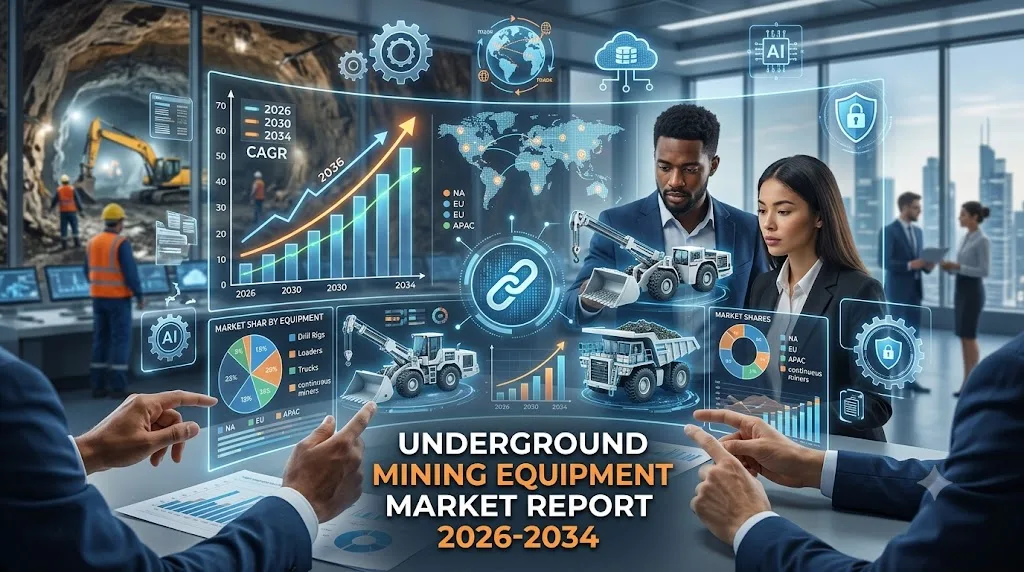
According to IMARC Group’s latest research publication, “Underground Mining Equipment Market: Global Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034”, The global underground mining equipment market grew from USD 30.9 Billion in 2025 to USD 32.0 Billion in 2026. Looking forward, IMARC Group expects the market to reach USD 40.4 Billion by 2034, exhibiting a growth rate (CAGR) of 2.96% during 2026-2034.
This detailed analysis primarily encompasses industry size, business trends, market share, key growth factors, and regional forecasts. The report offers a comprehensive overview and integrates research findings, market assessments, and data from different sources. It also includes pivotal market dynamics like drivers and challenges, while also highlighting growth opportunities, financial insights, technological improvements, emerging trends, and innovations. Besides this, the report provides regional market evaluation, along with a competitive landscape analysis.
How Underground Mining Equipment Is Reshaping Global Resource Extraction
- Asia Pacific accounts for the largest regional share in the global market, driven by rapid industrialization, government-backed mining expansion programs, and increasing demand for metals and minerals across China, India, South Korea, and Australia.
- Coal mining holds the leading application segment, supported by the continued reliance on coal for power generation across developing economies and the availability of large coal reserves in countries such as China and the United States.
- Longwalls dominate the type of mining segment, with demand driven by the need for high-efficiency, continuous coal extraction from large seams with minimal waste.
- In September 2026, Epiroc won a USD 64 million order from MMG Limited for underground equipment at the Khoemacau copper mine expansion in Botswana, including face drilling rigs, loaders, and mine trucks, with delivery starting in Q4 2026.
- The exhibition industry contributes USD 325 billion to the global economy annually, underlining the broader economic impact of sectors like mining, which depends on heavy equipment to sustain production cycles across over 32,000 exhibitions and trade events worldwide each year.
Key Trends in the Underground Mining Equipment Market
Download a sample PDF of this report: https://www.imarcgroup.com/underground-mining-equipment-market/requestsample
- Rising Demand for Minerals and Metals: Accelerating industrialization and infrastructure development across both developed and emerging economies are driving unprecedented demand for iron ore, copper, lithium, cobalt, and rare earth elements. The global shift toward electric vehicles and clean energy technologies has amplified extraction requirements, pushing mining companies to scale production capacity using advanced underground equipment capable of operating in deeper and more complex ore bodies.
- Safety-Driven Equipment Modernization: The inherently hazardous nature of underground mining has made safety compliance a primary investment driver. Companies are increasingly deploying proximity detection systems, automated roof support, collision avoidance technology, and ventilation control systems to meet stricter occupational health and safety standards. This shift toward safety-critical equipment is reshaping procurement decisions across all major mining geographies and directly expanding the total addressable market for advanced underground machinery.
- Automation and Remote-Control Adoption: Technological transformation remains one of the most disruptive forces in the sector. Autonomous loaders, battery-electric haulers, remote-operated drill rigs, and AI-integrated equipment are transitioning from pilot projects to full-scale deployment. The ability to remotely operate machinery in hazardous underground environments reduces worker exposure to risk while improving equipment utilization rates and overall productivity. Companies investing in automation capabilities are gaining a measurable competitive edge in both operational efficiency and long-term cost reduction.
- Electrification of Underground Fleets: Environmental regulations and net-zero commitments are accelerating the replacement of diesel-powered machinery with battery-electric vehicles across underground mining fleets worldwide. Battery-electric loaders, trucks, and drill rigs eliminate diesel particulate emissions in confined underground environments, improving air quality and reducing ventilation costs significantly. This electrification trend is creating substantial demand for new equipment categories and is prompting all major OEMs to expand their battery-electric product lines as a core strategic priority.
- Digitalization and IoT-Enabled Operations: The integration of IoT sensors, real-time performance monitoring platforms, and predictive maintenance systems is enabling mining operators to maximize equipment uptime and reduce unplanned breakdowns. Mining companies are increasingly leveraging CRM integrations, machine learning, and data analytics tools to optimize drilling cycles, haulage routes, and maintenance schedules. This digital transformation is driving demand for equipment that is both automation-ready and equipped with embedded telemetry and fleet management systems.
- Government Infrastructure Investment and Exploration Activity: Governments across Asia Pacific, Latin America, and Africa are actively increasing public investment in mining infrastructure, offering subsidies, simplifying permit processes, and fast-tracking new mine development to secure critical minerals supply chains. Increased exploration activities in previously untapped regions, particularly for lithium, copper, and cobalt, are creating strong pipeline demand for underground mining equipment as new projects move from feasibility to construction and operational phases.
We explore the factors propelling the underground mining equipment market growth, including technological advancements, consumer behaviors, and regulatory changes.
Growth Factors in the Underground Mining Equipment Market
- Critical Minerals Demand from Clean Energy Transition: The global pivot toward electric vehicles, battery storage systems, and renewable energy infrastructure has intensified demand for lithium, cobalt, nickel, and rare earth metals, nearly all of which require underground extraction. The metal mining segment is experiencing strong investment as automakers and battery manufacturers secure long-term supply agreements directly with mining operators, who in turn invest in advanced underground equipment to meet contractual production commitments.
- Equipment Replacement Cycles in Mature Mining Regions: North America and Europe house large inventories of aging underground mining equipment that are approaching end-of-life thresholds. Stringent emissions regulations, combined with rising maintenance costs on legacy diesel fleets, are accelerating replacement timelines. This creates a sustained demand cycle for new, technologically advanced equipment independent of commodity price fluctuations, providing a reliable baseline revenue stream for OEMs across developed markets.
- Expansion of Copper and Gold Mining in Latin America: Countries such as Chile and Peru continue to hold some of the world’s largest copper and gold deposits, attracting sustained capital investment from global mining majors. Infrastructure development, workforce training, and technology deployment at projects such as the Chuquicamata underground mine in Chile and new Peruvian copper operations are generating large, multi-year equipment orders that directly contribute to market volume growth in the region.
- Growth in Mineral Mining for Electronics and Pharmaceuticals: The mineral mining segment is benefiting from rising demand for rare earth elements used in consumer electronics, semiconductors, and pharmaceutical manufacturing. As global electronics production scales up, the need for underground mineral extraction and associated equipment grows proportionally. Sustainable extraction practices and environmentally compliant machinery are becoming mandatory differentiators for operators serving these high-value downstream industries.
- Middle East and Africa Emerging as High-Growth Markets: Countries in sub-Saharan Africa, particularly South Africa, Zambia, Botswana, and the DRC, are witnessing significant mechanization of underground mining operations. The transition from manual to mechanized mining methods is creating first-time demand for loaders, haulers, drill rigs, and ventilation equipment in previously underserved markets. Combined with growing FDI in African copper and platinum mines, this is positioning MEA as one of the fastest-expanding regions for underground mining equipment procurement.
Leading Companies Operating in the Global Underground Mining Equipment Industry:
- Caterpillar Inc.
- Epiroc AB
- Hitachi Construction Machinery Co., Ltd.
- J.H. Fletcher & Co.
- Komatsu Mining Corp
- Liebherr Group
- MacLean Engineering & Marketing Co. Limited
- Sandvik AB
- Sany Group Co., Ltd.
- SMT Scharf GmbH
- XCMG Group
Underground Mining Equipment Market Report Segmentation:
Breakup by Type of Mining:
- Longwalls
- Room and Pillars
Longwalls account for the largest share, driven by demand for high-efficiency and continuous coal extraction from large seams, with automation and improved roof support systems enhancing safety and operational output.
Breakup by Application:
- Coal Mining
- Metal Mining
- Mineral Mining
Coal mining represents the leading application segment, underpinned by the continued use of coal for power generation in developing economies and the availability of extensive coal reserves in China, the United States, and other resource-rich nations.
Breakup by Region:
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- North America (United States, Canada)
- Europe (Germany, France, United Kingdom, Italy, Spain, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
Asia Pacific holds the largest market share, driven by government initiatives to expand domestic mining output, rapid urbanization, and surging demand for raw materials across the region’s manufacturing-intensive economies.
Recent News and Developments in the Underground Mining Equipment Market
- September 2026: Epiroc won a USD 64 million underground equipment order from MMG Limited for the Khoemacau copper mine expansion in Botswana. The order, booked in Q3 2026, includes Boomer M20 S face drilling rigs, Simba E70 S production drilling rigs, Scooptram ST18 S loaders, and Minetruck MT65 S vehicles. Delivery is scheduled to begin in Q4 2026 and run through Q2 2028, with Epiroc also expanding its aftermarket facilities in Botswana to support regional mining operations.
- April 2026: Epiroc secured a USD 20 million (SEK 180 million) order from Mopani Copper Mines in Zambia for underground mining equipment including Minetruck MT436 and MT42 S haulers and Scooptram ST14 S and ST1030 loaders. The equipment is intended to enhance productivity and safety at the Nkana and Mufulira underground copper mines, with delivery commenced and scheduled for completion by the end of 2026.
- July 2025: Epiroc secured an order valued at SEK 235 million from Sociedad Punta del Cobre (Pucobre) in Chile for a fleet of underground mine trucks and a suite of digital solutions. The order, booked in Q2 2025, was aimed at boosting productivity, cost efficiency, and operational safety at Pucobre’s underground copper operations, reflecting the continued adoption of technology-integrated equipment across Latin America’s mining sector.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
About Us:
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: [email protected]
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302